
Div 296: Should You Withdraw Money From Super?
If you’ve spent years building a business and growing your super, Division 296 can feel like a penalty for doing exactly what you were encouraged to do. The natural reaction is to want to do something about it, and quickly.
My advice is to slow down. Division 296 tax doesn’t automatically mean you should withdraw money or restructure your super. If your balance is above $3 million, or heading that way, the first step is to understand three things: what the tax would cost you, what the alternatives would cost, and whether any change you make can be undone.
At North Advisory, we’re proactively working through our client base, because this is one of those pieces of legislation where there’s no blanket answer. The right response depends on each person’s tax position inside and outside super.
Division 296 tax: what’s changed and who it affects
Division 296 became law in March 2026 and applies from 1 July 2026. It adds two layers of tax:
- an extra 15% on the share of super earnings that relates to a total super balance above $3 million
- a further 10% on the share above $10 million.
Both thresholds are indexed to inflation from 2027–28.
The final version is noticeably softer than the original proposal. It now applies to realised earnings, such as interest, dividends, rent and realised capital gains, instead of taxing paper gains on assets you haven’t sold. The thresholds also apply per person, so a couple’s balances aren’t combined.
The detail that catches people off guard is how the tax arrives. The ATO assesses your liability using information your fund reports, and you’ll simply get a letter in the mail telling you how much you owe, payable within 84 days. That’s not the moment you want to start reviewing your strategy.
The first year is assessed on your total super balance at 30 June 2027, so the end of this financial year is the date that matters. For more background on how the rules evolved, read our earlier Division 296 tax update.
Your super is below $3 million. Should you still pay attention?
Yes, particularly if you’re within reach of the threshold.
Take someone with $2.8 million in super. All it takes is one good year in the markets to push them over. They haven’t changed anything, but their tax position has.
That’s why I’d suggest anyone with around $2.5 million start paying attention now. One or two strong years could be enough to take you into $3 million territory. With the first assessment based on balances at 30 June 2027, this year’s returns are the first ones that count.
For business owners, super is usually one part of a bigger picture. That picture might include investments in your own name, property, the business itself and the eventual proceeds of a sale. A strong year in the markets should be good news. It shouldn’t be the moment you discover your retirement strategy needed another look.
Should you withdraw money from super to avoid Division 296 tax?
This is where I’d urge the most caution, because we’ve already seen what happens when people rush.
When Division 296 was first announced a few years ago, some people panicked and started pulling large amounts out of their super. It hadn’t even been legislated, and the rules have since been watered down. A number of those people now can’t get the money back in.
Contribution caps and eligibility rules, which depend on your age and total super balance, can limit how much you’re able to put back. Once the money leaves, it can be very hard to return.
That matters because super is still, for many people, the most tax-effective place to hold their wealth, even with Division 296 applying to part of the earnings. When we ran some numbers, one thing stood out: if you have a high income in your personal name, it’s probably best to leave the money inside super. Moving it out may reduce your Division 296 exposure. But the earnings would then be taxed at your marginal rate, and you could end up paying more overall.
So the worst decision is making a major change before speaking to your accountant or adviser. There may be situations where withdrawing some money makes sense, but that should come out of the numbers, not out of concern about a new tax.
"Once that money leaves, it’s going to be very hard putting it back in."
What are your options for managing Division 296 tax?
Because Division 296 is assessed person by person, the options depend heavily on your circumstances. These are the areas we’re looking at with clients.
Using your personal tax position. For some self-funded retirees, low personal taxable income and available tax offsets can make holding some investments outside super worth considering. The comparison looks very different for someone still earning a substantial business income. That’s why we look carefully at the numbers before recommending any change.
Holding investments in another structure. A family trust can offer flexibility in how investments are owned and how income is distributed.
It also brings set-up costs, ongoing obligations and its own tax considerations. It needs to stack up on the whole picture, not on Division 296 alone.
Reviewing your SMSF’s cost base choice. If you run a [self-managed super fund](INSERT URL), the law includes a one-off choice to reset the cost base of the fund’s assets to their market value at 30 June 2026, for Division 296 purposes only. That limits Division 296 to gains made after that date, while the fund’s ordinary capital gains tax still uses the original cost base. The choice has three conditions:
- it covers all CGT assets the fund held at 30 June 2026
- it can’t be revoked
- it must be made by the due date of the fund’s 2026–27 return.
Whether it helps depends on the fund’s assets, which is why it’s worth reviewing now, not at lodgement time.
None of these is a solution in itself. Each one needs to be weighed against what you’re giving up.
“There’s not going to be a blanket solution for everyone.”
What should you review with your adviser now?
The first question is simple: is your super balance above $3 million, or could it realistically get there in the next year or two? If the answer is yes, talk to us or your accountant before you change anything.
From there, a review should cover:
- your current balance, and how close the next 30 June test date could take you to the threshold
- your personal income, and how investments would be taxed if you held them in your own name
- your other structures, including any family trust or company investments
- your SMSF, if you have one, and whether the cost base choice makes sense
- when you’ll need access to the money, and how much flexibility you want to keep.
For someone with a large super balance, these are decisions worth modelling, not making on instinct. Sometimes a review uncovers a better structure. Sometimes it confirms that leaving your money where it is remains the right call. Either way, you’ll know before the letter arrives.
If you’ve worked hard to build your super, the last thing you want is to undo years of careful planning because of a tax change. Division 296 deserves attention, particularly if your balance is approaching $3 million. But the right decision needs to work for your whole financial future, not just your next tax assessment.
Let's review your super strategy before you make changes
Division 296 may change how you approach your super, but any decision needs to make sense for your wider financial position and long-term goals.
At North Advisory, we’re reviewing clients’ superannuation strategies individually, looking at their tax position, investments and retirement plans before recommending any changes.
If you’re concerned about Division 296 or considering withdrawing money from super, get in touch with our team to discuss your options.
General information disclaimer: This article provides general information only and does not take into account your personal objectives, financial situation or needs. It is not personal financial, tax or legal advice. Please seek advice from a qualified adviser before acting.
About the author
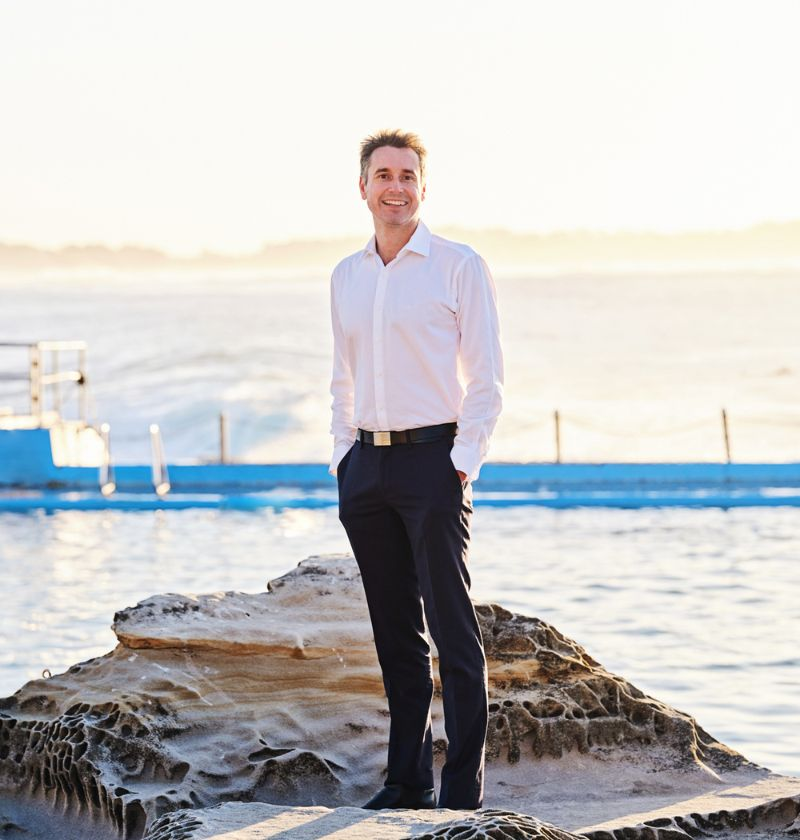
Cayle Petritsch - Director & Wealth Advisor
Cayle Petritsch, Director and Wealth Advisor, works with our existing clients who have recognised the importance of business owners making strategic financial choices not only for their company, but for their personal finances too.
Cayle saw a great opportunity to expand North Advisory’s services into SMSF/superannuation, personal wealth management, asset protection services and other crucial personal finance facets that business owners need to consider.
His approach to wealth management allows you to receive highly personalised wealth advice. Working closely with Marius, Cayle understands the unique needs of every client, from their lifestyle and business goals to their retirement plans.
Key Takeaways

Know your test date
The first Division 296 assessment uses your total super balance at 30 June 2027. This financial year’s market returns could decide whether you cross the threshold.
Watch from $2.5 million
A balance below $3 million doesn’t mean you’re safe. One or two strong years in the market can push a well-invested balance over the line.
Withdrawals are hard to reverse
Contribution caps and eligibility rules can stop you putting money back into super. Model the tax inside and outside super before moving anything.
SMSFs have a choice to make
The one-off cost base reset is irrevocable and due with the fund’s 2026–27 return. Review whether it suits your fund’s assets well before lodgement.
Driven by our values

Effortless and Seamless
On-Boarding Process
Intuitive and Knowledgeable
Direct Expert
Access

Useful and Articulate
Financial
Reporting

Forward
Thinking
Compliance Solutions

Streamlined
Tech
Integrated and Automated
FAQs
Does Division 296 apply to my combined super balance with my spouse?
No. Each person’s total super balance is tested separately against the $3 million and $10 million thresholds, so a couple’s balances aren’t added together. Your spouse’s position can still matter when reviewing how the household holds investments, future contributions and retirement income. That’s worth discussing with your adviser as part of a broader review.
When will I receive my first Division 296 tax bill?
The first year is based on your total super balance at 30 June 2027. Once funds have been reported to the ATO, it issues a notice of assessment to you personally, and the tax is due 84 days later. If it isn’t paid by then, the ATO can issue a release authority to your super fund.
Does Division 296 tax unrealised gains?
No. The final legislation taxes realised earnings, such as interest, dividends, rent and capital gains when assets are sold. It doesn’t tax paper gains on assets still held. SMSFs can also choose to reset their assets’ cost base to 30 June 2026 market values for Division 296 purposes, limiting the tax to gains after that date.
Can I withdraw money from my SMSF to avoid Division 296?
Only if you meet a condition of release, such as retiring after reaching preservation age. Even then, a withdrawal can mean paying tax at personal rates on future earnings, and contribution caps may stop you returning the money later. It’s a decision to model with your adviser before acting.
Should I stop contributing to super if I’m close to $3 million?
Not automatically. Stopping contributions may slow your balance’s growth, but it also means giving up super’s tax advantages on that money. The right answer depends on your income, contribution eligibility, other investments and retirement plans. A balance approaching the threshold is a reason to review your strategy, not a signal to stop.
How is Division 296 tax calculated?
Division 296 applies an extra 15% to the share of your super earnings that relates to the part of your balance above $3 million. For example, with a total super balance of $4 million, a quarter of your balance sits above the threshold. If your realised earnings were $200,000, the extra tax would apply to $50,000, adding $7,500. A further 10% applies to the share above $10 million. Your adviser can model the figures for your situation.
Who is the best person to give me advice on Division 296 tax?
Ideally, a financial adviser and an accountant working together. Division 296 affects your super, your personal tax position and how your investments are structured, so it rarely sits with one professional alone. At North Advisory in Dee Why, we look at all three together for clients across the Northern Beaches and Sydney. That helps make sure a change that reduces Division 296 doesn’t increase your tax somewhere else.
North Advisory’s Reviews  On
Flo Mitchell
4 weeks ago
Changed to this company in 2019 from former accountant and love their approach of organizing everything for me face to face with Xero set up plus being able to call as much as I need for set annual fee. They also picked up on something that was not done correctly by my former accountant and saved me $4k for this.
Timothy Cummins
A month ago
They the truly the best, Martin and Judy are so experienced, knowledgeable & professonal, also quite like speaking with Rose : ) all people are so lovely!
Michael Iera
2 months ago
Positive, Responsiveness, Quality, Professionalism, Value
Michael Iera
2 months ago
Excellent company in regards to service and professionalism. Very experienced in dealing with complex matters. Highly recommended.
Reach out we are here to help
Recognising the uniqueness of each business, we specialise in customised accounting services crafted to meet your specific needs and drive business growth.
Don’t hesitate to contact us if you’re ready to streamline your financial management with tailored solutions. Your business’s success is our primary focus. Fill in the contact form or call us to book an initial 30-minute chat.


Suite 6, 11 Oaks Avenue
Dee Why, Northern Beaches
NSW 2099
Australia